Negative gearing is changing. Here is what to do about it
From 1 July 2027 the only home in Australia you can negatively gear is a new build, and the 50% capital gains tax discount is replaced. Plenty of people will tell you what the rule says. Far fewer will tell you what it means for the property you already own, or the one you were about to buy. That is the part we are interested in.
What actually changed
Two measures, landing together on 1 July 2027, in the Treasury Laws Amendment (Tax Reform No.1) Bill 2026.
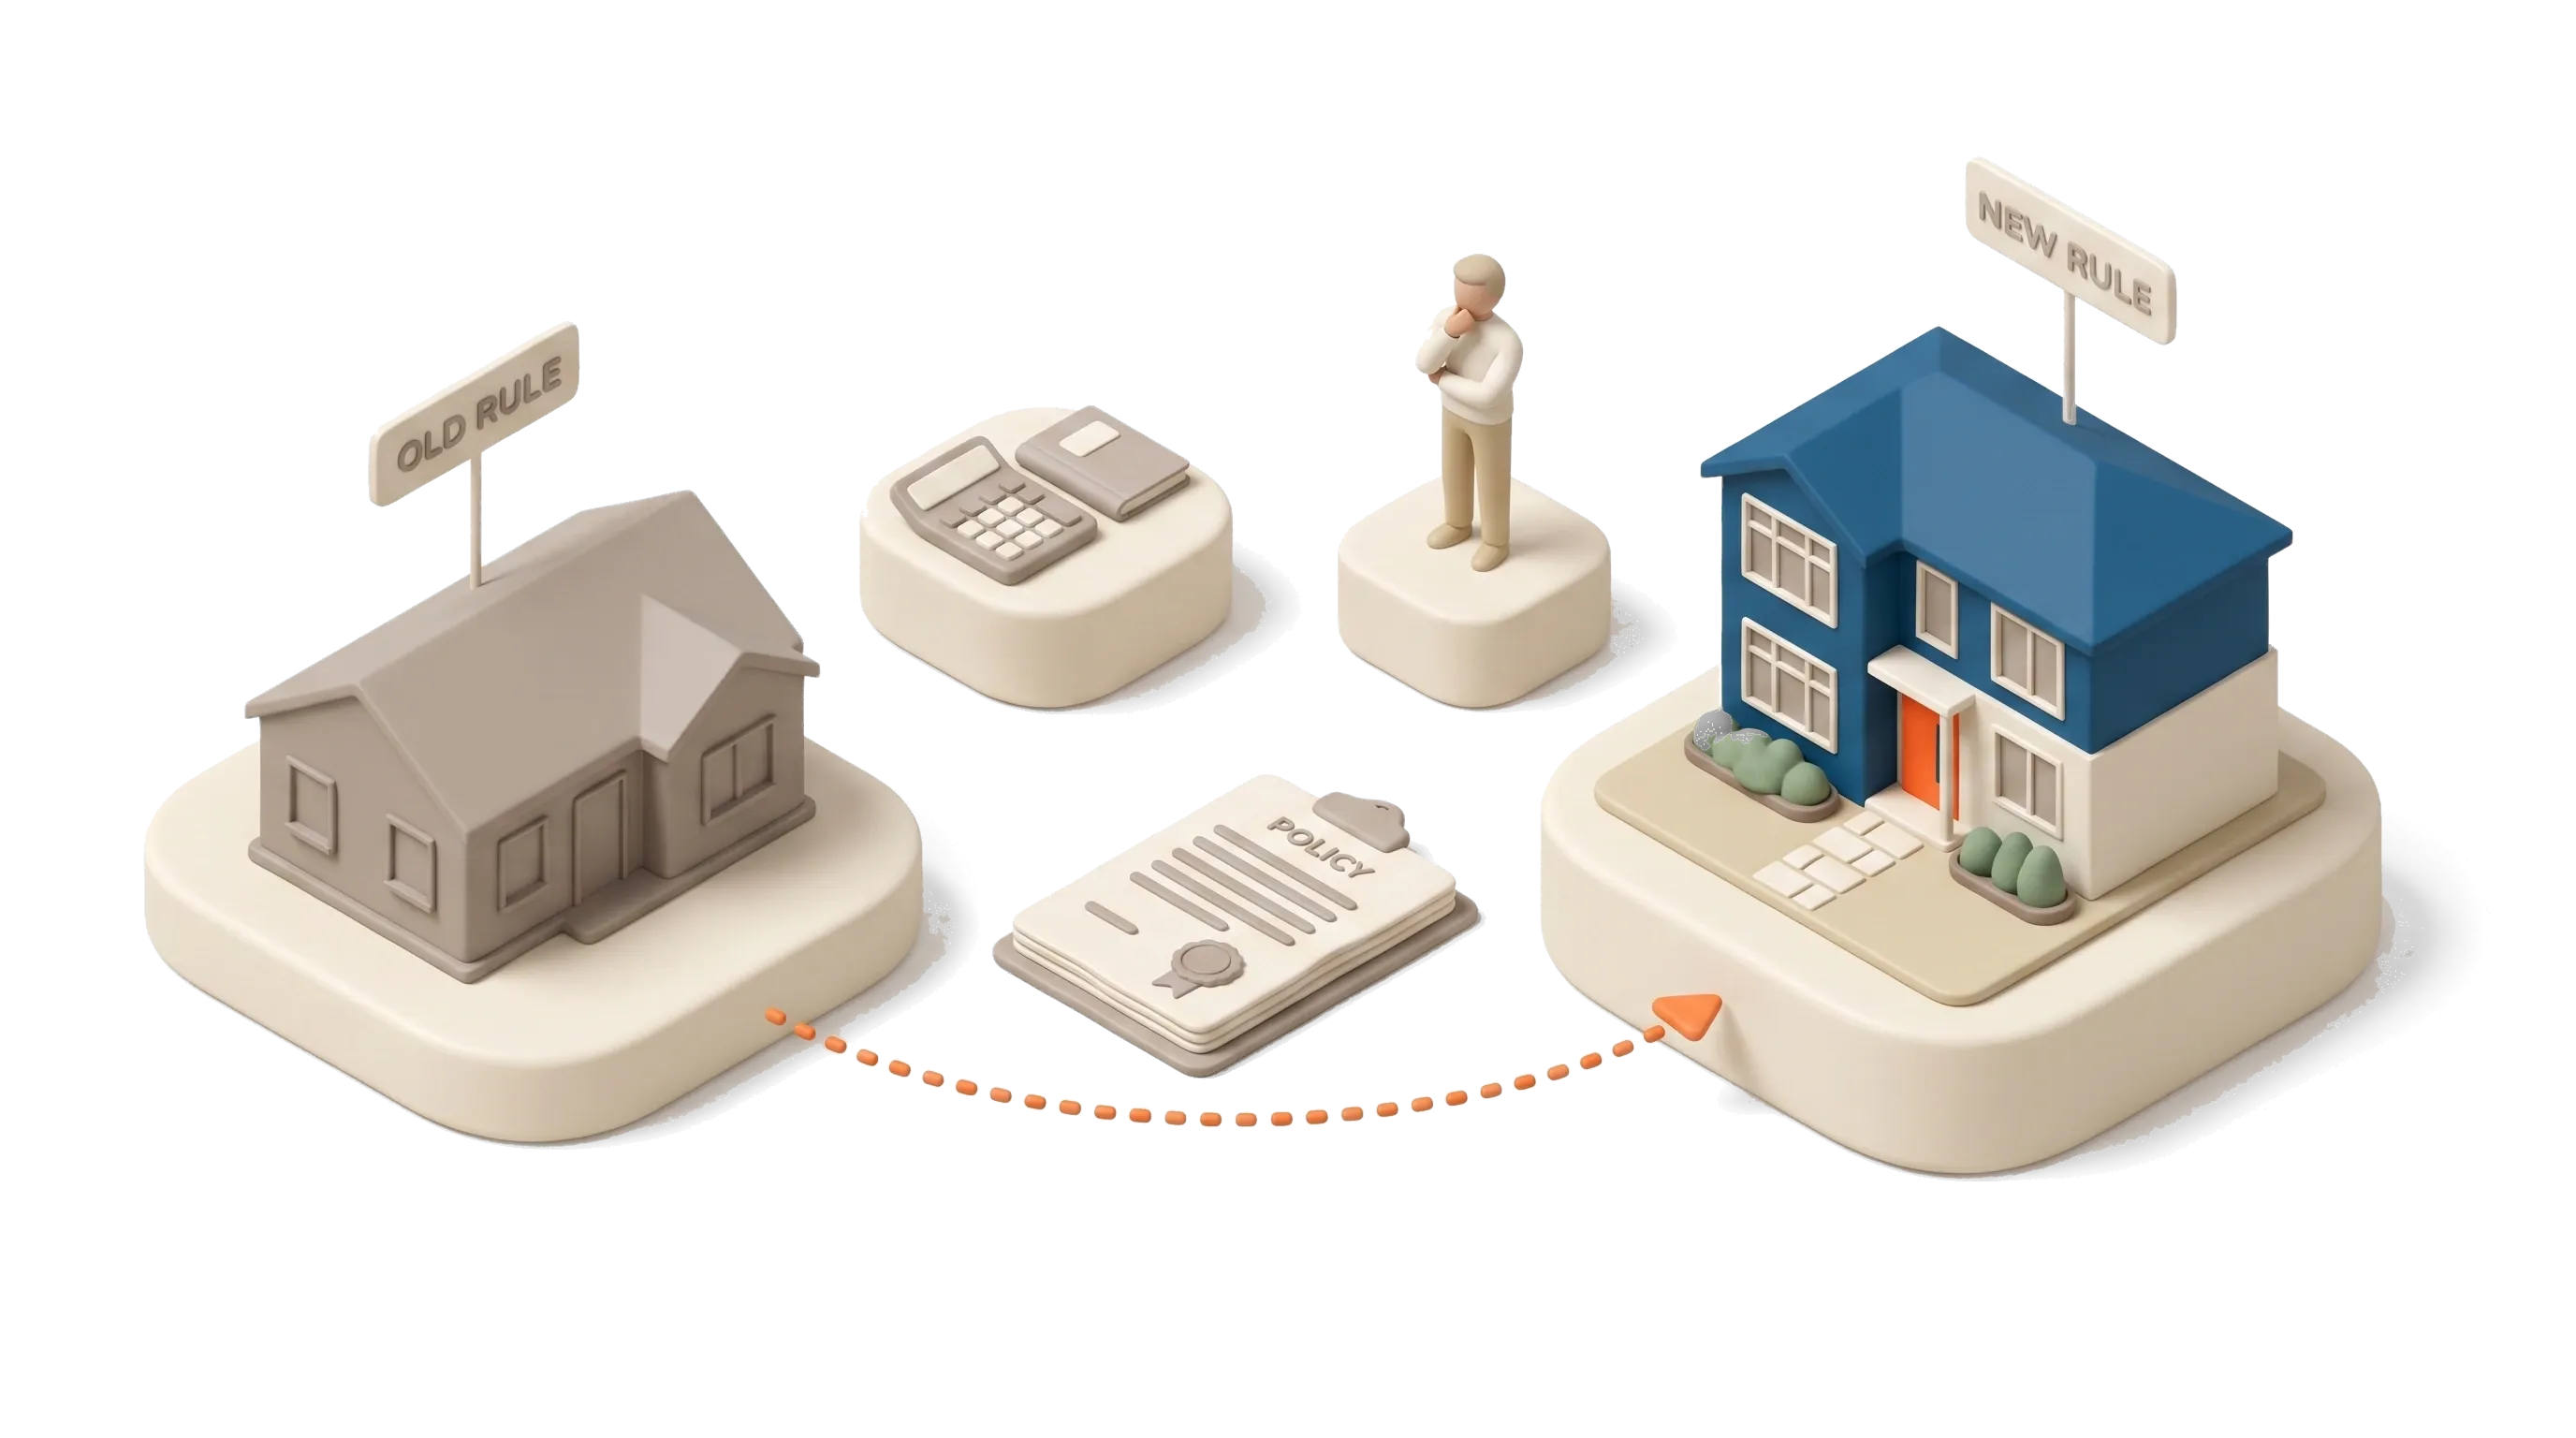
The first limits negative gearing to newly built dwellings. If a property makes a loss and it is not a new build, that loss no longer comes off your other income. The second replaces the 50% capital gains tax discount with an indexed cost base and a 30% floor on the discount.
Neither is a tweak. Together they remove the two tax settings that most Australian investors built their whole approach around, and they were rarely spoken about separately, because in practice they worked as a pair: wear the loss now, take the discounted gain later.
What it does to your numbers
Here is where most of the commentary stops short. The headline everyone repeats is that negative gearing has been abolished, which is both wrong and not the number that matters to you. It has been narrowed to new builds. The figure that decides what you do next is not the rule, it is your own annual shortfall and who is carrying it.
If you hold an established property that runs at a loss, that loss used to be shared. You covered the shortfall and the tax system gave part of it back at your marginal rate. From July 2027 on an established home, you cover all of it. Nothing about the property changes. The rent is the same, the mortgage is the same, and your out-of-pocket cost goes up by whatever the deduction was worth to you.
On the CGT side the direction depends on how long you hold and what inflation does. Indexation rewards long holds and punishes short ones, which is close to the opposite of what the flat 50% discount did. We work through it with real figures in the 2027 capital gains tax changes.
Everyone is asking the wrong question
The question filling every forum and comment section right now is "should I sell before 2027?". It is understandable, and it is the wrong first question, because it skips straight to an exit without checking whether the exit is the problem.
The better one is quieter. Was this property ever going to perform? A tax deduction is a subsidy on a shortfall, and a shortfall is what you get when the rent does not cover the debt. Plenty of investors have spent a decade covering one, telling themselves the tax back made it worthwhile, on a property that was never growing fast enough to justify either. For those holdings the tax change is not the cause of the problem. It is the thing that finally makes the problem legible.
If the property has genuine growth fundamentals, losing the deduction hurts but does not change the case. If it does not, the deduction was propping up a decision the numbers never supported. Those are two completely different situations, and the headline treats them as one.
None of this is a crystal ball, and the legislation still has detail to settle. But the direction of travel is hard to miss: the system is done subsidising the purchase of existing housing.
If you already own one
Three things worth doing before mid-2027, in this order.
Model your actual position. Not the suburb's average, yours. The annual shortfall, what the deduction is currently worth to you at your marginal rate, and what the property has genuinely grown at since you bought it, net of what you have tipped in along the way. Most people have never put those three numbers on the same page, and the exercise is often uncomfortable.
Check the grandfathering against the legislation, not a summary. This is the single most-searched question on the topic and the one where the summaries disagree with each other most often. Yours is a question for your accountant, with the bill in front of them.
Decide on the property, not the deadline. If you do sell, remember that a great many people are reading the same calendar you are. Selling into a queue is rarely the best-priced way out.
What counts as a new build
This turns out to be the load-bearing definition in the whole reform, and it is narrower than most people assume. A renovation is not a new build, however thorough. A knock-down rebuild, a subdivision with new dwellings on it, and a newly completed dwelling bought from the developer generally are, but the qualifying conditions matter and they are where the money is won or lost. We go through them properly in does your build count as a new build under the 2027 rules.
The reason the definition matters so much is simple. From July 2027 it is the line between a property whose shortfall is shared and one whose shortfall is entirely yours.
The four ways to get a new build
If new supply is where the tax system is pointing, the practical question is how an ordinary investor gets to it. There are four routes, and they are not equally available to everyone. You can buy a completed new build from a developer at retail. You can buy off the plan and carry the completion risk. You can develop something yourself, which is a real job rather than an investment. Or you can take part in a development as a co-owner and hold the finished property at what it cost to build rather than what it sells for.
Each has a different price, a different risk and a different amount of your time. We lay them out side by side, including the ones that do not require you to become a developer, in how to actually get a new build from 2027.
Why the entry price now matters more
This is the part that gets missed, and it is the most important consequence of the whole reform.
A new build bought at retail carries the developer's margin, the marketing cost and the sales commission inside its price. That has always been true. What has changed is that a tax deduction is no longer there to soften it, and the CGT change means you can no longer count on a discounted gain to rescue a purchase made too high. The entry price used to be one factor among several. It is now doing much more of the work.
Which is exactly why the gap between retail price and developer cost price stopped being a technicality and started being the decision. If the tax system is going to point investors at new supply, the investors who do best out of it will be the ones who did not pay retail to get there.
That is the whole reason we structure projects the way we do, and you can read how in manufacture capital growth by acquiring property at developer cost price.
Frequently asked questions
When do the negative gearing changes start?
From 1 July 2027. The measures sit in the Treasury Laws Amendment (Tax Reform No.1) Bill 2026. Until then the current rules continue to apply, which is why the window between now and mid-2027 matters more than the change itself.
Can I still negatively gear a property after 2027?
Yes, if it is a new build. From 1 July 2027 negative gearing is limited to newly built dwellings. An established home bought after that date cannot be negatively geared, so a loss on it no longer reduces your other income.
What happens to the 50% capital gains tax discount?
It is replaced. Instead of halving the gain, the new method indexes your cost base and applies a 30% floor to the discount. Broadly, the longer you hold and the lower inflation runs, the less the change costs you. Short holds in a high-growth market are hit hardest. This is general information, not tax advice.
Should I sell my investment property before 2027?
That is a question for your accountant, and the honest answer depends on your own numbers rather than the headline. What we can say is that selling into a rush of other sellers is rarely the best-priced exit, and that the change does not affect every holding equally. Read the rules first, then model your own position.
Do the changes apply to properties I already own?
The negative gearing limit applies to how the rules treat your deductions from 1 July 2027, not only to what you buy after that date, so existing holdings are in scope. Grandfathering detail is the single most-asked question on this topic and the most important thing to confirm against the legislation and with your own adviser rather than a summary.
Is this a recommendation to buy a new build?
No. This page is educational. We are property developers, so we have an obvious interest in new supply, and you should read us with that in mind. Whether any of it suits you depends on your circumstances, and we do not give tax or financial advice.
Working out what the change means for you?
Join the community and tell us which path fits. We share how our projects are structured privately, with people we have spoken to first.
Join the community