Housing development finance, explained without the brochure
Development finance is not a big mortgage. It is priced against a project rather than a person, drawn in stages against work actually completed, and repaid when the homes sell. Understanding that one difference explains almost everything else about it, including why so many feasible projects still cannot get funded.
The funding stack, from the bottom up
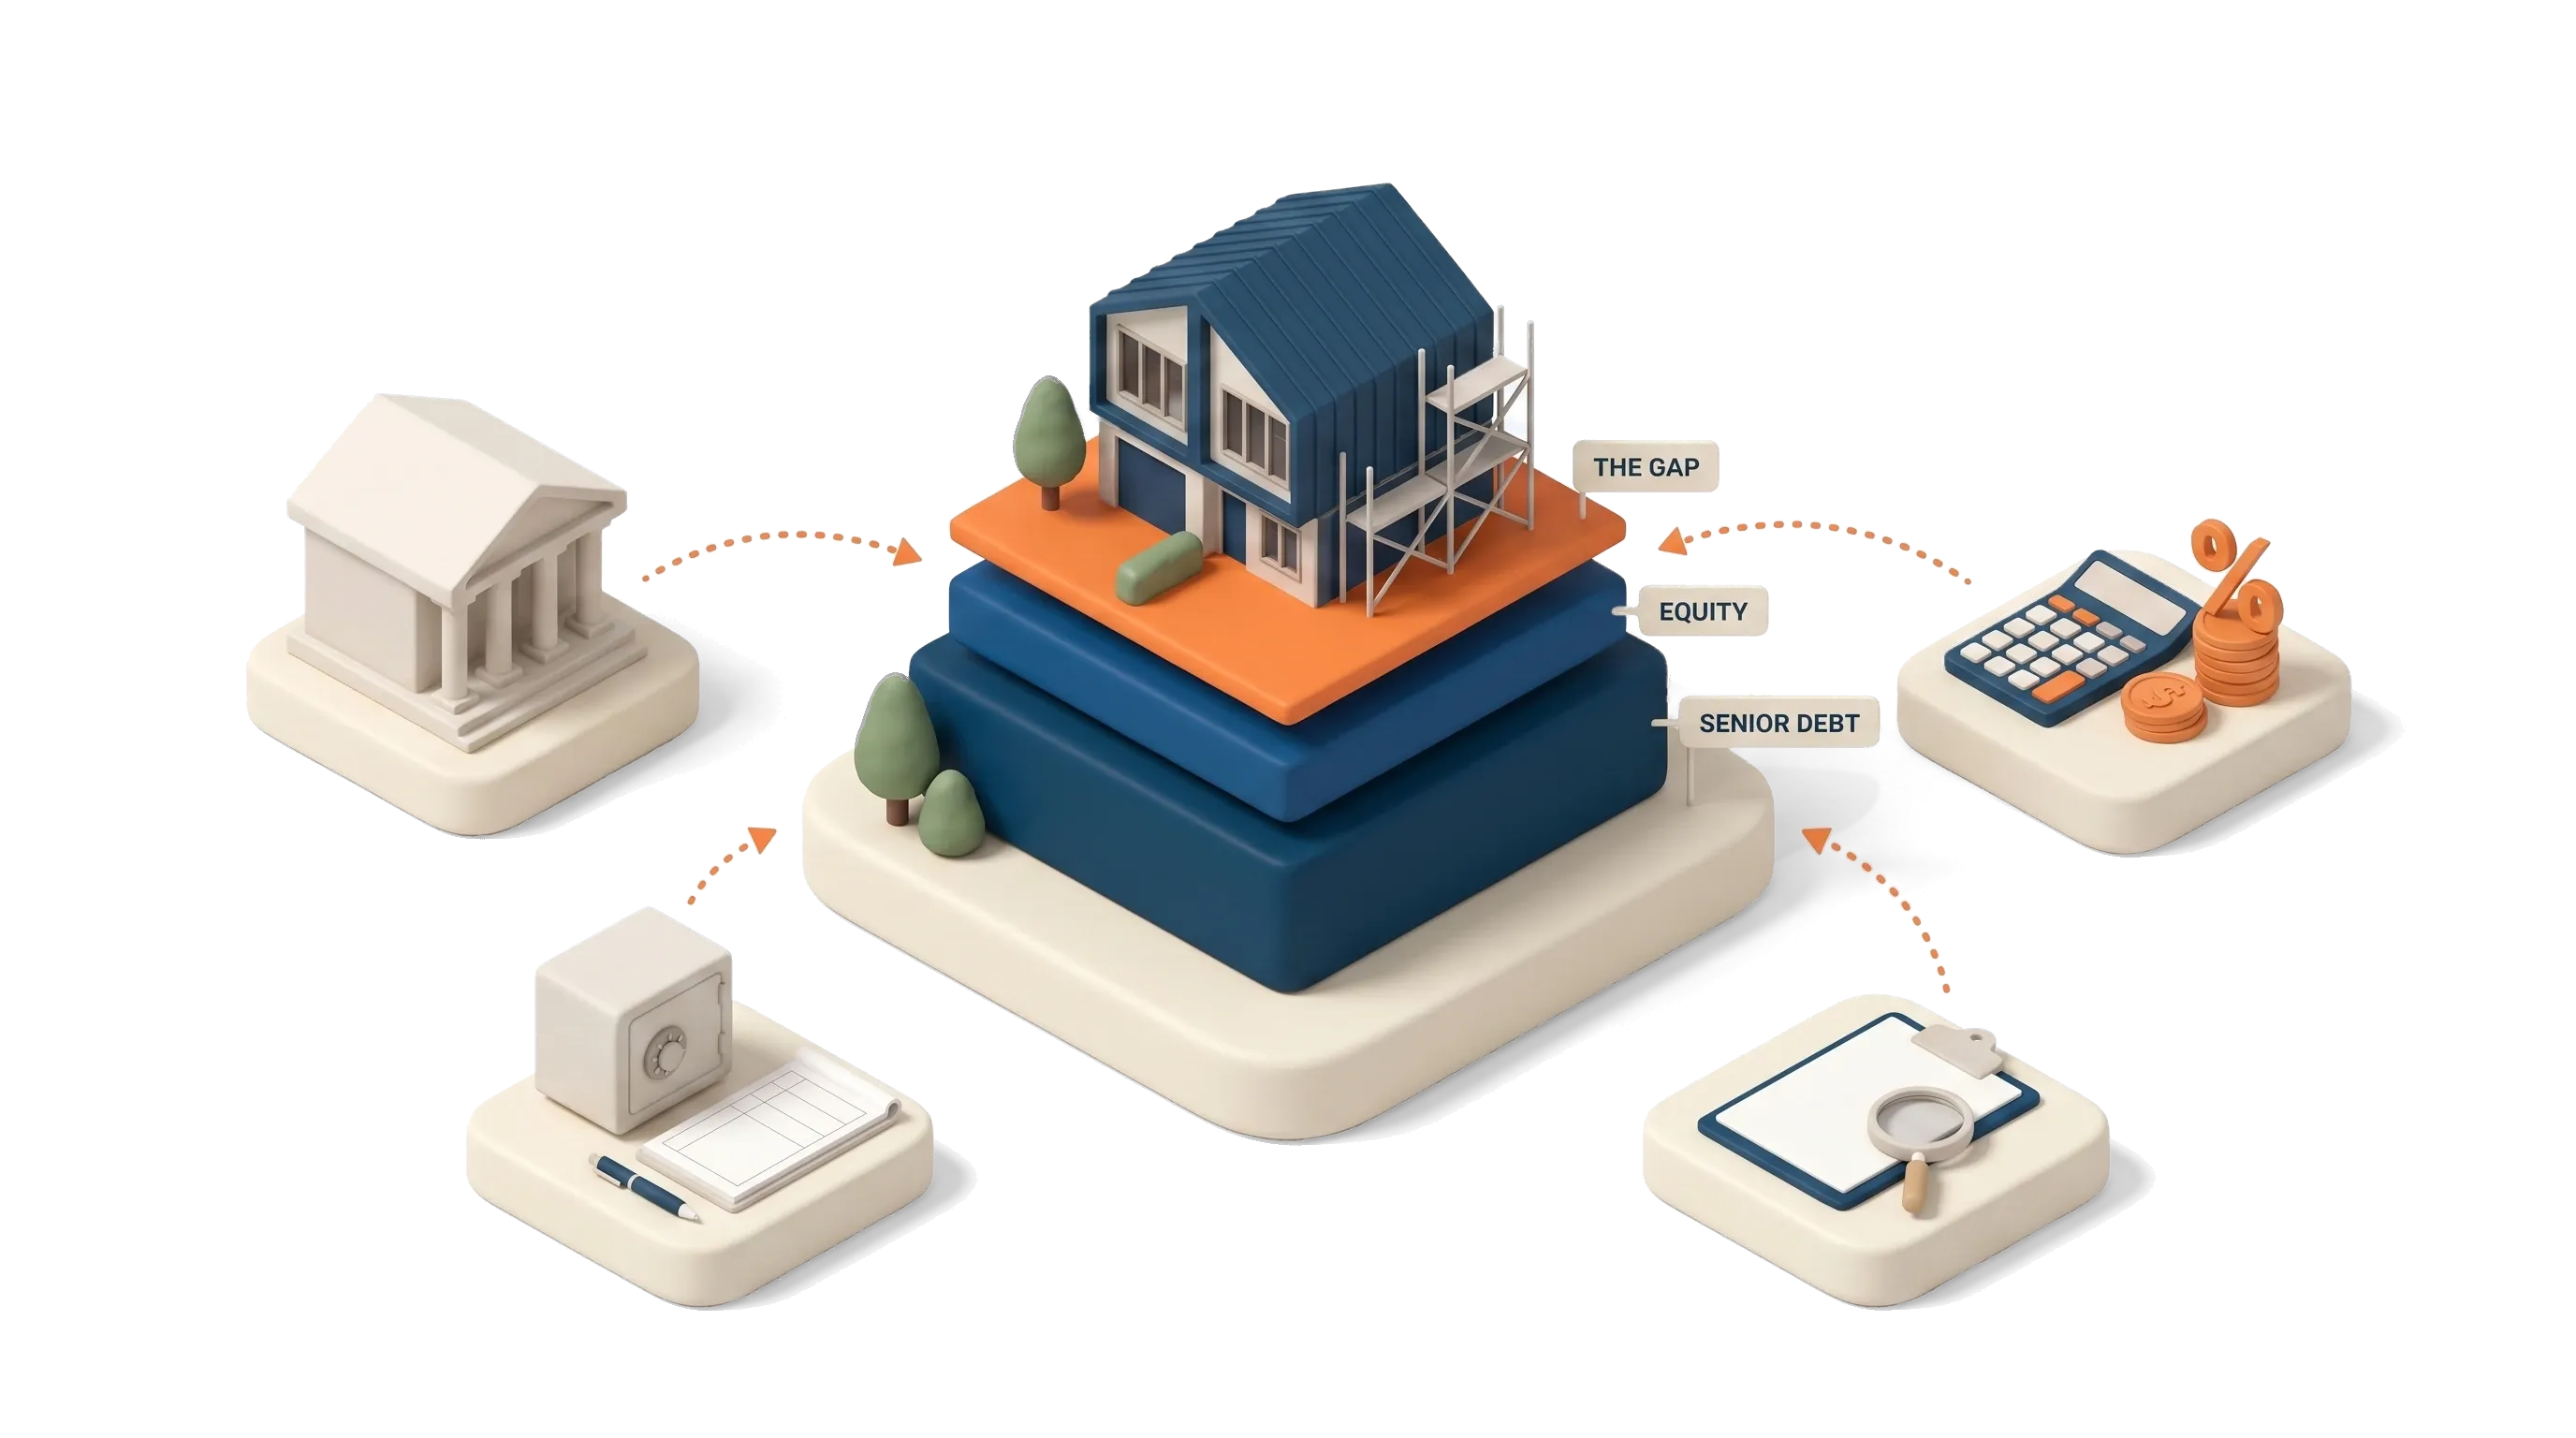
Every residential development is paid for by a stack of money, and the order matters more than the total, because the order decides who gets paid when things go well and who wears it when they do not.
Senior debt sits at the top of the queue for repayment and therefore charges the least. It is the bank or non-bank loan secured by a first mortgage over the site, advanced in stages against work completed and certified, not handed over in one go.
Mezzanine sits behind the senior lender and in front of equity. It exists because senior lenders will not fund the whole cost, and it prices that subordinate position accordingly. Useful, and expensive, and the layer that most often turns a thin margin into no margin.
Equity is last in the queue and first to absorb a loss. It is also the only layer that shares the upside, which is the trade.
Read down that list and you can see why a project with a healthy margin on paper still stalls. The senior lender will fund most of it. Somebody has to bring the rest.
What lenders actually assess
Ask a developer what a lender wants and you will hear "a good project". Ask a credit officer and you get a much shorter, less romantic list: the feasibility, the presales, the builder, the experience and the equity.
The feasibility has to hold up when someone else runs the numbers, which is a different test from holding up when you run them. Presales reduce the lender's exposure to what happens at the end, which is why a bank asks for them and a private lender will often price around them instead. The builder matters as much as the borrower, because the builder is who actually delivers the asset the loan is secured against. Experience is assessed bluntly and early. And the equity is the part that is genuinely non-negotiable, because it is the buffer that stands between a cost overrun and the lender's money.
We take that assessment apart properly in the guide chapter on the funding gatekeeper, and the blog post on the seven critical factors lists the thresholds.
Bank, non-bank or private credit
Three broad sources, and the honest way to describe the difference is speed and flexibility bought with margin.
Banks are the cheapest and the slowest, want the most presales, and are the most sensitive to their own regulatory capital position, which means their appetite for development lending moves with the cycle regardless of how good your project is. APRA's quarterly ADI statistics are the public record of that appetite.
Non-bank lenders move faster, accept fewer presales and charge more. Private credit sits further along the same line again: fastest, most flexible on structure, most expensive. The growth of non-bank and private lending in Australian property has been substantial enough that the Reserve Bank tracks it in the Financial Stability Review.
None of these is the right answer in general. The right answer depends on how much time you have, how many presales you can get and how much margin the project can afford to give away.
What it costs
Development finance is quoted in more pieces than a mortgage, and the headline rate is the least of them. Expect an establishment or application fee, the interest rate itself, a line fee on the facility, valuation and quantity surveyor costs, and often an exit fee.
We are not going to publish indicative rate ranges here, and you should be careful with anyone who does. Development finance is priced per project, the spread between a bank facility and private credit is wide, and a number written on a web page in 2026 will be quietly wrong within months. Get quotes against your actual feasibility. What matters for the decision is not the rate, it is the total finance cost as a share of project cost, and whether the margin still works with it in.
The gap nobody advertises
Here is the thing the finance brochures never lead with. Most small residential developments do not fail because the project was bad or the lender said no. They stall because the developer could not fund the equity layer.
The senior lender covers a substantial share of cost. The rest has to come from somewhere, and for a small developer with one site and a full-time job, that is exactly the amount they do not have sitting spare. So the site gets sold to someone larger, or the project waits, or the developer takes mezzanine at a rate that eats the margin they were building the thing for.
That gap is not a flaw in anyone's business. It is a structural feature of how development is funded in this country, and it is the reason the returns from development concentrate among people who already have capital. We go through the ways it gets bridged in five creative ways to fund a development.
How co-development changes the question
If the equity layer is the bottleneck, then the interesting question stops being "how do I borrow more" and becomes "who else could sensibly be in the equity".
That is what co-development is. A small number of investors take a share on title as tenants in common alongside the directors, the equity layer gets funded, and the growth the development manufactures is shared among the owners rather than paid away as margin to a financier. It is direct co-ownership of real property, not a pooled fund and not a financial product, and the directors carry the bank debt rather than the investors.
It is not a better answer than debt in every case. It is a different answer to a specific problem, and the problem it solves is the one that stops most small projects. The mechanics are in the co-development chapter, and what it looks like from an investor's side is on invest in property development for a cash return.
Frequently asked questions
What is housing development finance?
It is short-term funding for building homes rather than buying them. Where a mortgage is priced against your income and repaid over decades, development finance is priced against the project and repaid when the finished dwellings sell or refinance, usually inside 12 to 24 months. It is drawn down in stages against work completed, not advanced in one lump at settlement.
How much deposit or equity do I need for a development loan?
Lenders think in loan to cost and loan to development value rather than deposit. A senior lender typically wants a meaningful share of total project cost covered by your own equity, with the balance staged against construction. The exact proportion moves with the lender, the project and the cycle, which is why the equity gap is the most common reason a feasible project does not proceed.
Do I need presales to get development finance?
Often, though less universally than people assume. Presales reduce the lender's exposure to the sales risk at the end, so a bank will usually want a proportion of the end value contracted before it funds construction. Non-bank and private lenders will frequently accept fewer presales, or none, and price that additional risk into the rate.
Can I get development finance without experience?
It is harder, and it is one of the first things assessed. Lenders look at what you have completed before, at what scale, and who is actually building it. A first-time developer with a strong builder, a genuine feasibility and real equity is fundable; the same person with none of those is not. Partnering with an experienced developer is a common way around it.
Is development finance regulated like a home loan?
Generally not in the same way. Lending to a business or a special purpose vehicle for a commercial purpose sits outside the consumer credit protections that apply to an owner-occupier mortgage. That is a meaningful difference in your rights, so understand which regime you are in before you sign. This is general information, not credit or financial advice.
What is mezzanine finance in property development?
It is funding that sits between the senior loan and the developer's equity. It ranks behind the senior lender for repayment and ahead of equity, so it carries more risk than the bank debt and costs more accordingly. It is typically used to bridge the gap between what the senior lender will advance and what the developer can put in.
Want to see how a project is actually funded?
The guide walks the whole process, feasibility to settlement. Join the community if you would like to talk about the equity side.
Join the community