Market news
Interest Rates and Property Development: What the Latest Move Means for Small Developers
TL;DR: A rate move hits a small development in three places at once: the cost of finance, buyer demand at the end, and the feasibility that ties them together. But higher rates often lift rental demand even as they cool buying, so a data-led, yield-focused project can stay resilient. The move is not to trade the decision, it is to respect feasibility, choose locations on evidence, and favour growth the build creates over growth borrowed from the cycle.

When the cash rate moves, do you know what actually changes for someone creating property rather than buying it?
Have you watched a project that stacked up comfortably start to look marginal, without a single line of the budget changing?
And do you know why the same rate rise can hurt your end value and help your rent at the same time?
Every time the Reserve Bank of Australia moves the cash rate, or holds it, the coverage reaches for the same script: mortgages, repayments, household budgets. Ahead is the part it skips. The three places a rate move hits a small development at once, why the rent side often tells the opposite story, and what we actually do at FracHaus when a decision lands.
This is commentary. For the framework behind it, see where and when to buy residential property.
Interest rates hit a property development in three places at once
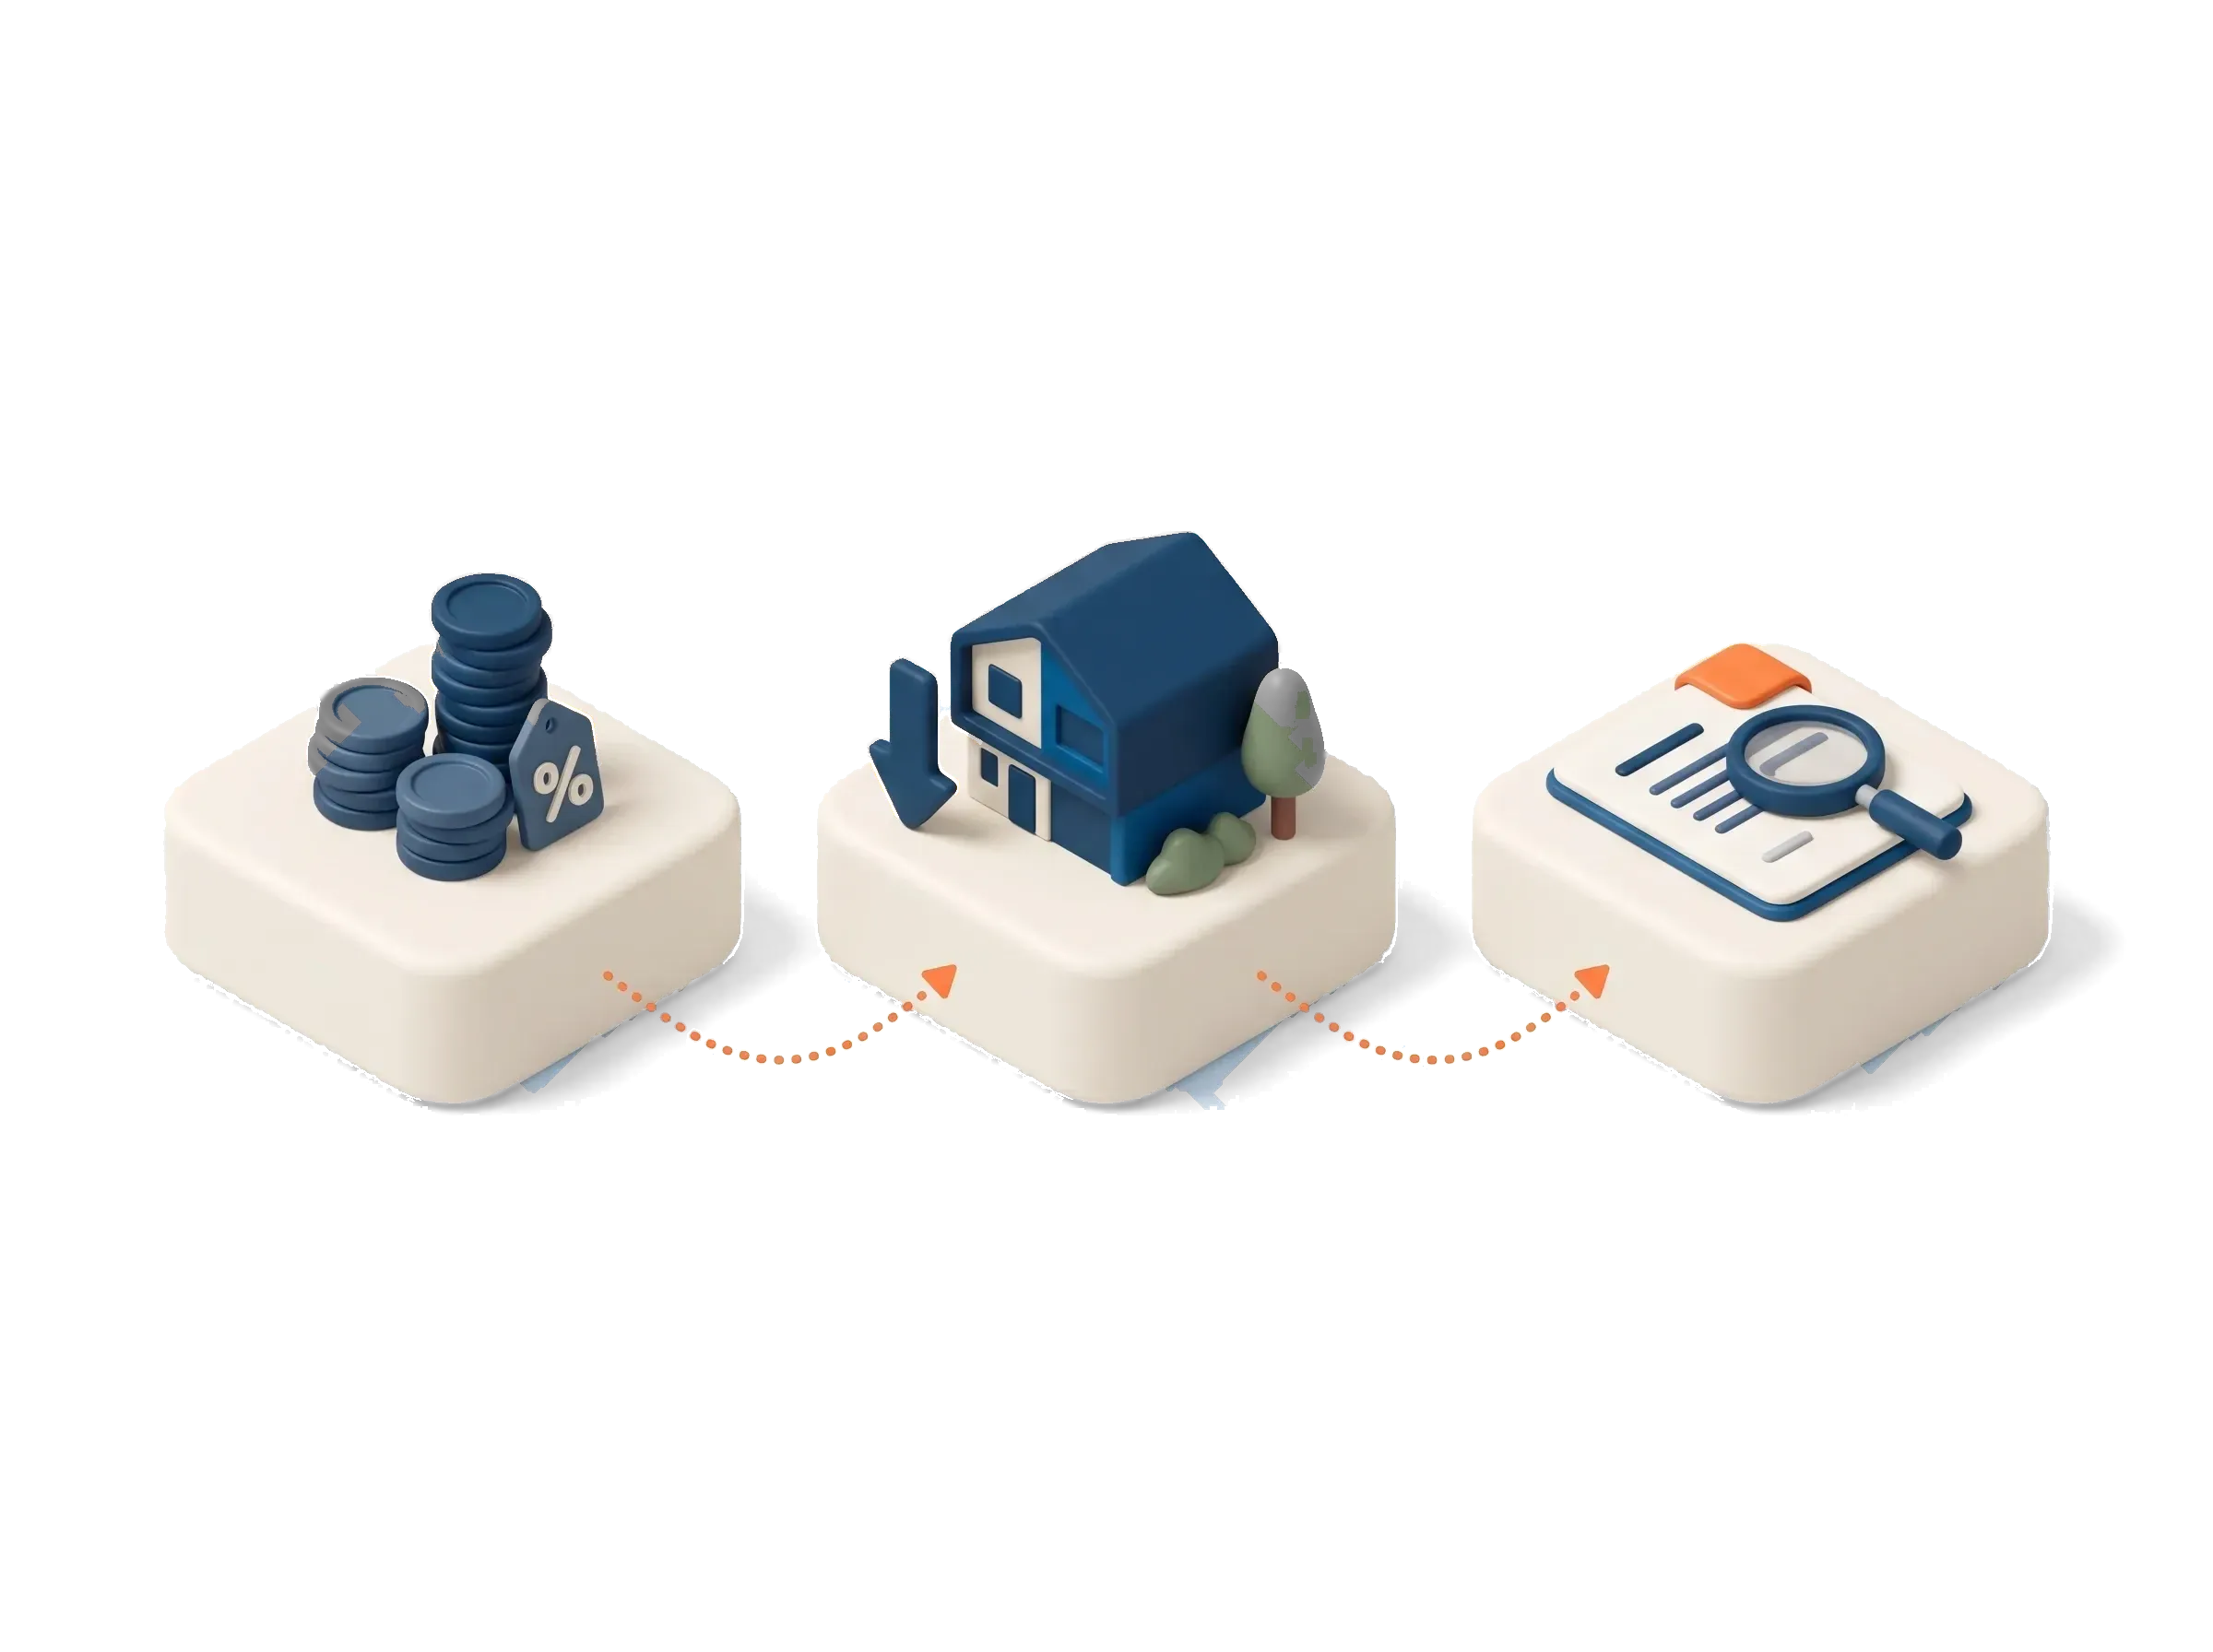
A rate change does not touch a project in one spot. It hits three:
- The cost of finance. Development is funded with debt. When rates rise, the interest on that debt rises, and since it accrues over the whole build, even a small move compounds into real money on a project that runs eighteen months.
- Buyer demand at the end. Higher rates reduce borrowing capacity, which softens what buyers can pay. That flows straight into your end value, the single most important input in a feasibility.
- Feasibility itself. Squeeze finance costs up and end values down at the same time, and a project that stacked up comfortably can suddenly sit on a knife edge.
This is why developers watch rates far more nervously than a headline about repayments would suggest.
When rates rise, rental demand often rises with them
Here is the part that gets missed. When rates rise, fewer people can afford to buy, so more people rent for longer. That pushes rental demand up and vacancy down, exactly when new supply tends to slow because higher finance costs make projects harder to start.
The result can be counter-intuitive: a softer buying market and a stronger rental market at the same time. For an investor focused on yield, that mix is not necessarily bad news. It is one reason acquiring a home at developer cost price, where you start from a stronger yield, can be resilient when rates are elevated.
What we actually do with a rate move
We do not try to trade rate decisions. We do three practical things:
- Re-stress the feasibility. Every live assessment gets its finance-cost and end-value assumptions checked against the new reality.
- Lean harder on location. In a tighter market, the gap between a genuinely in-demand location and a marginal one widens. Data-led site selection matters more, not less.
- Favour projects that don’t need the cycle. The whole point of investing in property development for a cash return is that the return comes from the build, not from betting on where rates go next.
The takeaway
A rate move is not a reason to panic or to celebrate. It is a reason to check your numbers. Developers and investors who respect feasibility, choose locations on evidence, and avoid relying on the cycle tend to come through rate turbulence in better shape than those who don’t.
More reads: reading building-approvals data · the 2026 downturn and what it changes when you buy new · rental yields at a seven-year high while prices fall · the pillar hub: property market news.
Frequently asked questions
How do interest rates affect a property development?
A rate move hits a project in three places at once. It raises the cost of the debt funding the build, it reduces what buyers can borrow and therefore pay at the end, and it squeezes the feasibility that connects the two. That combination is why developers watch rate decisions far more closely than a headline about household repayments would suggest.
Why does a small rate rise cost a development so much?
Because development interest accrues on drawn debt across the entire build, and it capitalises rather than being paid down. On a project running eighteen months with millions drawn, a fraction of a per cent compounds into real money. The same rise that adds modestly to a homeowner's monthly repayment can remove a meaningful slice of a project's margin.
Do rising interest rates increase rents?
Often, yes, and it surprises people. When rates rise, fewer households can afford to buy, so more of them rent for longer, which pushes rental demand up and vacancy down. At the same time higher finance costs make new projects harder to start, so supply slows. The result can be a softer buying market and a stronger rental market simultaneously.
What happens to a feasibility when rates change?
Two of its most important inputs move in the same unhelpful direction: finance costs go up and end values come under pressure. A project that stacked up comfortably can sit on a knife edge. The disciplined response is to re-stress every live feasibility against the new numbers rather than assuming the original margin still holds.
Should small developers fix their development finance?
Development finance is usually variable and priced per project, so the choice is rarely as simple as it is for a home loan, and fixing can carry break costs if the project sells earlier than planned. What matters more is whether the feasibility survives a rate rise from where it sits today. This is a question for your finance broker, since terms vary widely between lenders.
Sources
- Cash rate target — Reserve Bank of Australia, accessed August 2026